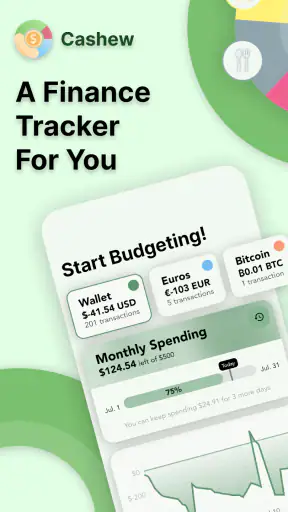
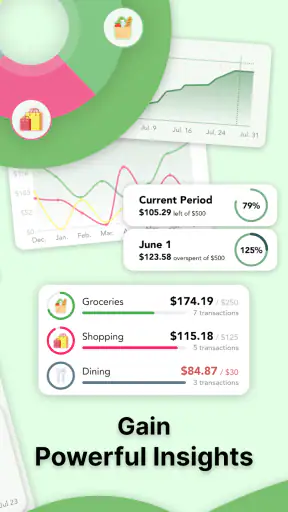
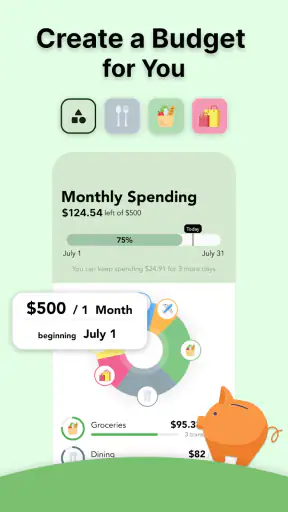
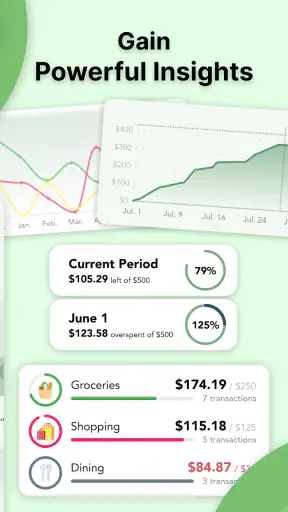
I spent time with Cashew—Expense Budget Tracker as a practical finance app rather than treating it like a simple receipt notebook. Its main appeal is straightforward: it gives me a place to record spending, organize a personal budget, and look back at where my money went. That sounds ordinary, but the difference between an expense tracker I abandon and one I keep using usually comes down to how little effort it demands during a busy day.
Cashew is free to download, and the app is aimed at Everyone, so it is approachable for someone who has never used a budgeting tool before. It comes from Dapper App Developer and has built a strong audience, with more than half a million installs and a 4.7 average from roughly twenty-seven thousand ratings. Those figures do not replace personal testing, but they do match my impression that this is designed for everyday users rather than finance specialists.
The best way to understand it is to see it as a habit-building tool. It will not magically fix overspending, and it is not a substitute for a bank account or a full accounting system. What it can do well is make the small act of recording a purchase feel manageable enough that I actually keep doing it. That consistency is where the value appears.
How I built a useful daily workflow
My first recommendation is not to begin by trying to model every detail of personal finances. I would start with the expenses that matter most: food, transport, household purchases, subscriptions, and larger bills. The goal is to create a clear picture quickly. If the first setup becomes a long classification project, the app starts feeling like work before it has shown any benefit.
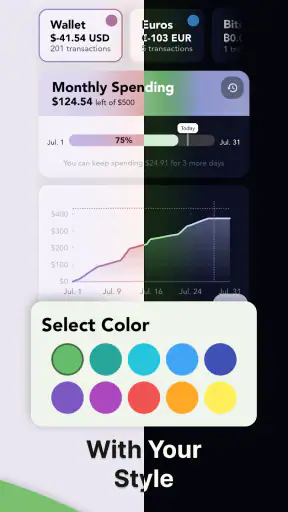
A simple daily routine works better. After paying for something, I record it while the amount and purpose are still obvious. For a quick coffee or a grocery trip, this takes only a moment when the categories are already familiar. At the end of the day, I can review the entries together and correct anything that looks unclear. Both approaches are reasonable; the better one depends on whether I am more likely to forget a purchase or dislike interrupting my routine.
A realistic example is a Saturday with a bus ride, a supermarket visit, and lunch away from home. Entering those as separate expenses gives me a much more useful picture than remembering only the total spent that day. The individual entries reveal which type of spending is creating pressure. That distinction matters because “I spent too much this weekend” is vague, while “food outside the home is repeatedly pushing my plan off course” gives me something I can change.
I also found it helpful to decide in advance how precise my categories need to be. Someone who wants a fast overview may use broad groups such as food and transport. Someone managing a tight monthly plan may benefit from separating groceries, restaurants, delivery, fuel, and public transit. Cashew becomes more useful when the categories answer a question I genuinely ask, not when they exist merely because a budget app allows detailed organization.
The same principle applies to notes. I would add a note when it explains an unusual purchase, a shared expense, or a payment that I might otherwise misunderstand later. Writing a long explanation for every entry slows the routine without improving the review. A short identifying detail is usually enough.
Turning records into decisions
Recording expenses is only half the workflow. I get more from the app when I set aside a regular moment to inspect the pattern. That review does not need to become a daily budgeting ceremony. A brief check can answer practical questions: Did an irregular bill distort this period? Are small purchases accumulating? Is a category too broad to guide a decision? Is a budget unrealistic because it ignores a recurring obligation?
This is where a tracker differs from a calculator. A calculator tells me what I spent once. A maintained record helps me compare my intention with my behavior. If I repeatedly underestimate a category, lowering the number on paper will not solve the problem. I either need to change the behavior or make the plan more honest. Cashew is useful in that moment because it puts the evidence in front of me.
I would not wait until the end of a month to discover that the system is inconvenient. During the first few days, I would notice which entries take too many taps, which categories feel ambiguous, and which recurring expenses I am likely to overlook. That early adjustment is an underrated part of using any expense tracker. A system that feels natural at the beginning of a spending cycle is easier to maintain than one I keep postponing.
Settings and organization choices worth checking
Cashew has a current version of 6.6.11, and it runs on Android 7.0 or later. For most Android users, that makes compatibility fairly broad, but I would still check the device requirement before planning a long-term setup on an older phone. The app is also available as a finance-focused mobile tool, so I would think about how it fits my actual phone habits rather than assuming it will replace every other financial service I use.
The most important settings are the ones that affect clarity. I would review the currency, the way categories are named, and the structure of the budget before entering a large history of purchases. A category name that seems obvious today can become confusing later, especially if several people share the same device or if I track personal and household spending together.
It is worth deciding whether a category describes the item purchased or the purpose of the money. For example, a supermarket trip might contain food, cleaning products, and personal-care items. Splitting every receipt can create precision, but it can also make entry tedious. Keeping the whole receipt together is faster, although the later analysis is less detailed. I prefer the second approach unless a particular category is important enough to influence a real decision.
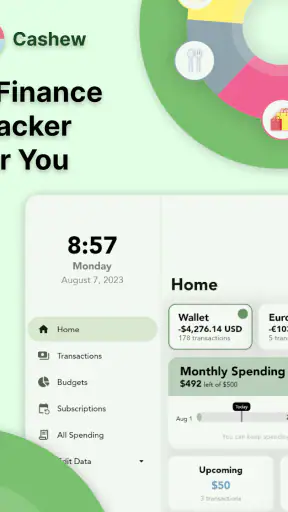
Budget periods deserve similar attention. A monthly plan feels natural for salary-based finances, but it can hide the timing of bills if several large payments arrive close together. I would consider the dates when money actually comes in and goes out, then use the app consistently. The best period is not the one that looks most elegant; it is the one that helps me avoid a cash-flow surprise.
Another useful setting habit is to keep the first version intentionally small. I would begin with a handful of categories and expand only when the review shows a meaningful reason. This prevents the common mistake of creating a complicated structure that looks impressive but takes too long to maintain. Good budgeting is often less about capturing every detail and more about capturing the details I will act on.
Because Cashew includes in-app purchases ranging from $1.49 to $19.99 per item, I would pay attention to which parts of the experience are included and which optional additions matter to my workflow before spending money. The free starting point makes it easy to test the basic habit first. I would not purchase anything simply because I feel I ought to make the app “complete”; I would only consider an add-on if it removes a genuine obstacle in the way I use the tracker.
Making the app fit real life
The most effective setup is the one I can use when I am distracted. I would keep category labels short enough to recognize at a glance and avoid creating multiple versions of the same idea. “Eating out,” “restaurants,” and “takeaway” may all be useful distinctions, but only if I can apply them consistently. If I hesitate every time I enter a purchase, the data becomes less reliable and the habit becomes fragile.
I would also establish a rule for shared spending. If I pay for a meal for friends, I can record the full amount, record only my portion, or use a note to mark the amount expected back. None of these approaches is universally correct. The important point is to choose one before similar situations occur, because changing methods halfway through makes later totals difficult to interpret.
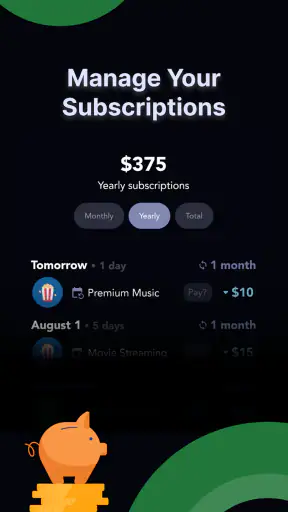
For subscriptions and recurring bills, I would create a repeatable review habit rather than trusting memory. At the start of a period, I can check whether the expected payments still match reality. This is particularly useful for services that quietly continue after I stop using them. An expense tracker cannot decide whether a subscription deserves to stay, but it can make the recurring cost harder to ignore.
Faster patterns that keep the record accurate
Experienced use is less about entering more information and more about reducing hesitation. I would use the same category for the same kind of purchase every time, even if the label is not perfect. Consistency makes later comparisons meaningful. A beautifully detailed record with changing rules is less useful than a modest record built on stable rules.
One pattern I like is the two-pass method. The first pass is quick capture: amount, category, and a short description when needed. The second pass is review: I look for missing entries, unclear classifications, and purchases that should be included in a budget decision. This separates speed from analysis. Trying to analyze every purchase while entering it is what makes many trackers feel slow.
Another practical pattern is to group review tasks. Instead of repeatedly checking tiny details throughout the day, I can spend a few minutes at a chosen time checking the latest records. That works especially well for people who pay with several methods and might otherwise lose track of cash purchases. The trade-off is obvious: delaying entry increases the risk of forgetting, so I would use delayed review only when I have a reliable memory cue.
I would also use a “why did this change?” question whenever a category suddenly rises. The answer may be a one-off event, a timing issue, or a new routine that is becoming permanent. Treating every increase as a failure leads to unrealistic budgets. Treating every increase as harmless leads to drift. Cashew is most helpful when I use its records to investigate rather than judge myself.
For couples or families, the app can still be useful as a personal tracking tool, but I would be careful about assuming that one set of entries automatically represents the whole household. Shared finances require agreed rules: who records joint expenses, whether reimbursements are included, and how transfers are treated. Without that agreement, the totals may look precise while describing only one person’s side of the picture.
The same caution applies to cash. Cash spending is easy to forget because there may be no digital trail to remind me. I would record it immediately or keep a short reminder until I can enter it. If cash is a major part of my routine and I rarely carry my phone, any mobile tracker will depend heavily on discipline. In that situation, a small paper note used temporarily may be a useful companion, even though the final record belongs in Cashew.
Small habits that improve the results
I would avoid editing old entries casually. If I change a category, amount, or date, I would know why I changed it. Corrections improve the record; silent changes made just to make a budget look better do not. A monthly review is a good time to fix genuine mistakes and leave a brief note for unusual transactions.
I would also separate planned money from actual spending in my thinking. A budget is an intention, while an expense entry is an event. If I confuse the two, I may feel successful simply because I planned a low amount, even when my actual behavior says otherwise. The app becomes more valuable when I compare the plan with reality without trying to force reality to match the plan.
For irregular expenses, I would not judge a period in isolation. Annual fees, gifts, repairs, and travel can make one month look unusually expensive. The useful response is to recognize the pattern and prepare for it, not to pretend the expense does not belong. A tracker is strongest when it helps me see these less frequent obligations before they become emergencies.
Where the app reaches its limits
Cashew is a good fit for someone who wants hands-on awareness of spending, but it is not automatically the best choice for every financial setup. If I want a fully automated view of several bank accounts, I would look for a service built around account connections and automatic transaction imports. Manual tracking gives me control and awareness, but it also asks me to remember each purchase.
That manual element is both a strength and a weakness. Entering a transaction forces me to notice it, which can improve spending awareness. At the same time, a missed entry creates an incomplete picture. Someone who wants to open an app and see everything synchronized without regular input may find this approach frustrating.
I would also look elsewhere if I needed formal bookkeeping, business accounting, invoicing, tax records, or elaborate financial reporting. A personal expense tracker can support those activities, but it should not be mistaken for a professional accounting package. The simpler design is an advantage for household budgeting and a limitation for complex financial administration.
There is a similar trade-off around detail. A person who enjoys building a highly customized financial model may eventually want more specialized tools. Cashew makes sense when the priority is a usable record and a repeatable budget routine. If every category, account, and rule needs to behave like a spreadsheet, a dedicated spreadsheet or accounting application may offer more flexibility, even though it may require more setup.
Privacy-minded users should also make their own comfort assessment before putting sensitive financial information into any app. I would use a sensible level of detail and avoid entering information that is unnecessary for the budgeting decision I am trying to make. The app can help organize spending without requiring me to turn every transaction into a personal diary.
Finally, the free price is attractive for trying the basic workflow, but optional purchases mean that long-term users should understand their own needs before paying. I would use the free experience long enough to discover whether I actually record expenses consistently. Paying for features cannot repair a habit that I have not established.
My verdict after building a repeatable routine
Cashew—Expense Budget Tracker works best when I treat it as a quiet daily practice rather than a financial command center. Its strongest quality is the balance between structure and approachability: there is enough organization to reveal spending patterns, but the idea is simple enough for a beginner to understand. The developer, Dapper App Developer, has positioned it as a personal finance app, and that focus is clear in the way I use it.
I would recommend it to someone who wants to understand where money goes, prefers entering purchases deliberately, and is willing to spend a few minutes reviewing the results. It is especially useful for people who have tried complicated budgeting systems and abandoned them because maintaining the system became harder than managing the money.
I would be more cautious about recommending it to someone who expects automatic bank synchronization, professional accounting controls, or a complete household finance platform. Those needs point toward a different kind of tool. Cashew is not a replacement for every alternative in the finance category; it is a practical option for personal expense awareness and budget discipline.
The app has been available since August 21, 2023, and its current version is 6.6.11. I mention that because ongoing use matters with a finance tool: I want an app that fits into a routine I can keep, not one that only looks useful during setup. Its Everyone rating also makes it approachable for a broad audience, from a student tracking daily spending to a household trying to bring recurring costs under control.
My final advice is to start modestly, choose categories that support real decisions, and review the record on a predictable schedule. Use fast capture when life is busy, then correct and interpret the entries later. Keep the rules consistent for shared purchases, cash, subscriptions, and unusual bills. With those habits, Cashew becomes more than a list of expenses: it becomes a clear feedback loop between what I planned and what I actually do.
That is why I would recommend giving it a fair trial before judging it. The app cannot create discipline on its own, but it can make disciplined behavior easier to repeat. For a free finance app with optional in-app purchases, that is a sensible starting point for anyone who wants a clearer, more honest view of everyday spending.


